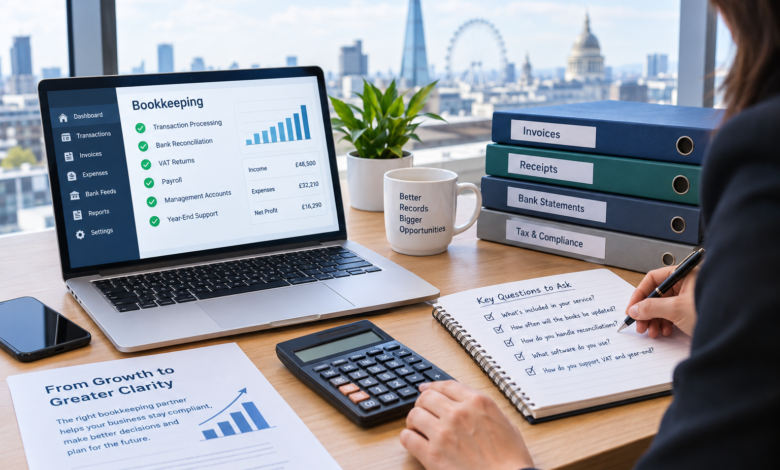
A founder can often manage bookkeeping with a bank feed and a spreadsheet when a business has a handful of transactions each month. That arrangement looks very different once the company is paying suppliers regularly, issuing dosens of invoices, employing staff, registering for VAT or operating through several payment platforms.
At that point, bookkeeping stops being mainly about entering transactions. The quality of the underlying records begins to affect management accounts, VAT returns, Corporation Tax work, cash-flow reporting and the amount of time spent answering accounting queries later.
That is why businesses comparing bookkeeping companies in London should look beyond the question of who can categorise transactions. Service frequency, reconciliation procedures, document management, software arrangements and the way bookkeeping connects with year-end accounting can all matter.
For a growing SME, the right arrangement is usually the one that keeps records sufficiently current and structured for the decisions and reporting the business actually needs.
When Growing Businesses Outgrow DIY Bookkeeping
There is no particular turnover figure at which a business suddenly becomes too large to manage its own books. Complexity matters more.
A small consultancy issuing ten invoices a month may remain straightforward even with reasonably high revenue. An ecommerce company with marketplace settlements, payment-processing fees, refunds, stock purchases and hundreds of monthly transactions can create substantially more bookkeeping work at a much earlier stage.
Problems often become visible when bookkeeping starts being postponed. Bank transactions remain uncategorised. Supplier invoices sit in inboxes. Directors cannot easily explain the difference between the accounting balance and the bank balance. Records may eventually be brought up to date, but only after a substantial clean-up exercise.
For limited companies, record keeping is not simply an administrative preference. Companies must maintain accounting records that show money received and spent as well as their assets and liabilities. HMRC guidance also requires companies to retain relevant records for Corporation Tax purposes, generally for six years from the end of the financial year concerned, subject to certain circumstances where they must be kept longer.
Growth can therefore create two separate reasons to change the bookkeeping model. The first is compliance: the records must remain adequate. The second is operational: owners increasingly need financial information before the accountant prepares the annual accounts.
Signs that the existing system is becoming difficult to manage
Common warning signs include month-end work repeatedly rolling into the following month, unreconciled bank balances, missing purchase documents, inconsistent expense categories, unexplained director transactions and figures that cannot easily be traced back to supporting records.
Another important signal is dependence on one person. If nobody else understands how invoices, receipts and bank information are organised, routine bookkeeping can become fragile when that individual is busy or unavailable.
Outsourcing does not automatically solve those problems. A bookkeeping provider still needs complete information from the business. The real objective is to establish a repeatable process for collecting, recording, checking and reviewing financial data.
What to Compare in a London Bookkeeping Provider
Bookkeeping firms in London can operate quite differently even where their service descriptions appear similar. Before comparing fees, establish exactly what work is included.
Some providers concentrate almost entirely on transaction processing. Others operate as part of an accountancy practise and can connect the bookkeeping with VAT, payroll, management accounts, and annual compliance work.
Neither structure is automatically preferable. What matters is whether the scope fits the business.
Transaction processing is only the starting point.
Entering sales and purchase transactions is a basic bookkeeping function, but growing businesses should ask what happens afterwards.
Does the provider reconcile every relevant bank and credit-card account? Are payment processors reconciled as separate accounts? How are outstanding customer balances reviewed? What happens when the bookkeeping team cannot identify a transaction?
Those questions reveal more than a broad promise to “keep the books up to date”.
Reconciliation is particularly important because accounting records can contain apparently valid entries without matching what has actually moved through the bank. A duplicated expense, omitted payment or incorrectly allocated transfer may not become obvious until balances are checked against independent records.
Ask how frequently the books will be updated.
Frequency should reflect how the figures will be used.
Quarterly bookkeeping may be sufficient for a relatively simple owner-managed company where records are mainly required for compliance. A growing company using monthly management information will normally need transactions processed and reconciled more regularly.
There is little value in receiving detailed financial reports every month if the underlying bookkeeping is several weeks behind.
The question is therefore not simply, “Do you provide monthly bookkeeping?” It is, “By what point each month will the previous period normally have been processed and reviewed?”
How to Compare Bookkeeping Companies in London
Different business models call for different types of support. A useful comparison starts with the provider’s operating model rather than its marketing description.
| Service model | Often suitable for | Points to examine |
| Independent bookkeeper | Smaller businesses with relatively straightforward records | Availability, cover during absence, software familiarity and escalation arrangements |
| Bookkeeping specialist | Businesses with significant transaction-processing requirements | Reconciliation procedures, reporting, document handling and communication process |
| Accountancy practise with bookkeeping services | SMEs wanting bookkeeping connected with accounting, VAT or tax work | Exact scope, handover between teams and frequency of review |
| Outsourced finance function | Businesses needing bookkeeping alongside management reporting or wider finance support | Reporting depth, controls, approval processes and responsibility split |
The table should not be treated as a hierarchy. A capable independent bookkeeper may be entirely appropriate for one company, while another may benefit from having bookkeeping and statutory accounting handled within the same professional relationship.
Growing businesses should also think about what happens next. A service that suits the company today may become restrictive if transaction volumes increase rapidly or management requires more detailed reporting.
Digital Records and Bank Reconciliation Matter More as a Business Grows
Modern bookkeeping is increasingly built around digital records, bank feeds and accounting software, but software alone does not guarantee accurate books.
Automation can import transactions. It cannot always determine why money moved, whether VAT treatment is correct, whether a payment belongs to a director’s loan account or whether two similar-looking transactions represent different business activities.
Someone still needs to review exceptions and reconcile the records.
For VAT-registered businesses, the digital element also has a regulatory dimension. Making Tax Digital for VAT requires VAT-registered businesses to maintain specified VAT records digitally and submit VAT returns using compatible software, unless an exemption applies. HMRC also sets rules around digital links where more than one software product is used.
That makes software compatibility a sensible question when evaluating bookkeeping services in London. Businesses should understand where invoices are stored, how expenses are submitted, whether bank feeds are used and how information passes between systems.
A bank feed is not the same as a bank reconciliation.
The distinction is easy to miss.
A bank feed imports transaction information into bookkeeping software. A reconciliation checks whether the accounting record corresponds with the bank statement and investigates differences.
A growing company may have several current accounts, savings accounts, business credit cards, foreign-currency accounts, and payment platforms. Each can create reconciliation work.
For businesses receiving money through platforms such as card processors or online marketplaces, the amount reaching the bank may also differ from the gross customer payment because fees, refunds or other deductions have been taken before settlement.
A bookkeeping process should therefore preserve the economic detail of the transaction rather than treating every bank deposit as sales income without investigation.
Where Bookkeeping Should Connect With Wider Accounting Work
Bookkeeping creates the transaction-level information used elsewhere in the finance function. The cleaner that information is, the easier it becomes to prepare VAT returns, accounts and useful management reports.
For that reason, some SMEs prefer to keep bookkeeping and their wider accounting work within one accountancy relationship.
Clarkwell & Co., for example, provides bookkeeping services for London businesses covering areas including transaction recording, bank reconciliation and the organisation of financial records. Businesses looking for a service connected with wider accounting requirements can review bookkeeping support from Clarkwell & Co. as one example of this type of model.
The practical consideration is integration rather than brand name. If one organisation maintains the books and another prepares the accounts, the handover can still work perfectly well. Both parties simply need clear records, agreed responsibilities and an efficient way to resolve questions.
Problems arise when nobody owns the gaps between them.
Reporting: Decide What You Actually Need From the Books
A common mistake is to assume outsourced bookkeeping automatically includes management reporting.
It may not.
Standard bookkeeping generally focuses on recording and reconciling transactions. Management accounts go further by organising financial information into reports designed to help people understand business performance.
The distinction matters because not every SME needs the same reporting.
A director who mainly wants reliable records for annual accounts may need very little beyond well-maintained ledgers and basic reports. A business employing a management team, monitoring several revenue streams or preparing for rapid expansion may want monthly profit-and-loss information, balance-sheet reporting, debtor analysis and comparisons against budgets.
Before paying for additional reporting, ask which decisions the reports are intended to support.
If no one will review a 20-page monthly pack, producing it achieves little. A smaller collection of reliable figures delivered consistently may be much more useful.
Questions to Ask Before Outsourcing Bookkeeping
A productive provider discussion should focus on workflow rather than simply asking for a price.
The following questions help establish how the service will operate:
- What bookkeeping tasks are included, and what falls outside the quoted service?
- How often will transactions and bank accounts be processed and reconciled?
- Who investigates unidentified transactions, and how are queries sent to us?
- Which accounting and document-management systems will be used?
- How will invoices, receipts and expense records be supplied?
- Are VAT bookkeeping requirements included where relevant, or handled separately?
- What reports will we receive, and how frequently?
- Who reviews completed bookkeeping work before a period is closed?
- What happens if transaction volumes increase significantly?
- How is information handed over to whoever prepares our annual accounts and tax returns?
- Who retains access to the accounting data if the engagement ends?
- Which responsibilities remain with our internal team?
These questions also make quotations easier to compare. A low monthly figure can look attractive until it becomes clear that reconciliation, historic corrections, or routine accounting queries are charged separately.
Conversely, a more comprehensive quotation may contain services a simple business does not need.
The meaningful comparison is scope against scope.
Data Access and Internal Responsibility Still Matter
Outsourcing bookkeeping changes who performs the work; it does not remove management responsibility for providing accurate source information or overseeing the company’s finances.
Directors should therefore retain appropriate access to the accounting system and understand the basic reporting produced from it.
The business should also decide who internally is responsible for sending purchase invoices, confirming unusual payments, explaining director expenses and responding to bookkeeping queries.
Without that ownership, queries can sit unanswered for weeks and gradually reduce the reliability of the records.
Good bookkeeping arrangements tend to make responsibility explicit. Staff know where documents go. The provider knows who can answer questions. Cut-off dates are understood. Unresolved items are visible rather than disappearing into a generic suspense account indefinitely.
Choosing the Right Bookkeeping Service Model
The appropriate service model depends less on company age than on transaction complexity, reporting needs and how much finance administration the business wants to retain internally.
A founder-led consultancy with modest transaction volumes may simply need monthly reconciliation and well-organised records. A VAT-registered retailer processing large numbers of payments may need frequent transaction matching and closer attention to digital records. A larger SME may want bookkeeping connected directly with management accounts, payroll and year-end accounting.
Pricing should be considered in the same context.
Ask what drives the fee. Some providers price according to transaction volume; others use fixed service packages or determine costs according to the amount and complexity of work involved.
Also consider what would happen if the company doubled in size. Switching providers is possible, but changing accounting processes during rapid growth creates unnecessary work. It is reasonable to ask whether the proposed system can accommodate additional accounts, employees, payment channels, or reporting requirements.
The objective is not necessarily to buy the largest service package available. It is to avoid paying for a process that is already close to its limits.
Good Bookkeeping Should Make the Business Easier to Understand
Bookkeeping is often discussed as a compliance function, but its usefulness extends beyond preparing information for HMRC or Companies House.
Accurate records make straightforward questions easier to answer. Which customers still owe money? Which suppliers remain unpaid? Has a particular cost increased? Do the accounting records agree with the bank? Is the information being supplied to the accountant complete?
For sole traders and partnerships, HMRC similarly requires records of business income and expenditure so that tax returns can be prepared and transactions identified. Supporting evidence can include invoices, receipts and bank records.
The precise bookkeeping process will differ according to the legal structure and tax position of the business, but the underlying principle is consistent: financial records should be sufficiently organised to explain what has happened.
Choosing Bookkeeping That Can Keep Up With Your Business
Growing businesses rarely need outsourced bookkeeping because entering numbers has suddenly become impossible. They need it because the volume and importance of their financial information have outgrown an informal process.
When comparing bookkeeping firms, London businesses should focus on scope, reconciliation, digital record-keeping, reporting frequency, software access and the connection between bookkeeping and wider accounting work. Price matters, but only after those factors are understood.
The right model may be an individual bookkeeper, a specialist outsourcing provider or an accountancy practise offering business bookkeeping alongside other services.
What matters is that the arrangement fits the company’s current complexity and can remain dependable as the business develops. Well-maintained books should not merely exist for the year-end. They should give owners, directors and advisers a clearer record of what is happening throughout the year.